Executive Summary An LLC may hold S Corporation shares when its federal tax classification allows an eligible shareholder to be treated as the owner. Disregarded single-member LLCs may qualify, while partnership- and corporation-classified LLCs generally do not. An ineligible shareholder can terminate the S election and trigger C Corporation tax treatment. Ownership changes should be coordinated with tax, Read More
Why Should Business Owners Consider a Trust Protector?
Executive Summary A Trust Protector may provide additional oversight and flexibility for trusts holding business interests. Depending on the Trust Agreement, the role may include replacing trustees, exercising defined oversight powers, and responding to certain changes in circumstances. California’s Uniform Directed Trust Act may apply to some Trust Protector arrangements. Clear authority and coordinated Read More
When Should Business Owners Consider a Kovel Agreement?
Executive Summary A Kovel Agreement may help preserve attorney-client privilege for certain confidential communications involving professionals who assist legal counsel. Business owners may encounter these arrangements during tax controversies, valuation disputes, and succession planning. Routine accounting, tax preparation, and valuation services are not automatically protected. The professional’s role and Read More
What Are the Criticisms of a Bridge Trust?
Executive Summary A Bridge Trust® combines domestic administrative convenience with an offshore asset protection framework established before a legal dispute arises. Assets are transferred into the trust at the outset, with due diligence conducted during the initial funding process rather than after a creditor claim occurs. An independent Trust Protector can declare an Event of Duress, activating protective Read More
QSST vs ESBT: How Business Owners Can Protect an S Corporation After Death
Executive Summary Not every trust can hold S Corporation stock indefinitely. A QSST generally supports one current income beneficiary and requires current income distributions. An ESBT can accommodate a broader beneficiary structure but is subject to different trust-level tax rules. QSST and ESBT elections are subject to specific filing and eligibility requirements. Coordinating your trust, tax strategy, and Read More
Does Landlord Insurance Protect Your Personal Assets? Why California Rental Property Owners May Still Need an LLC
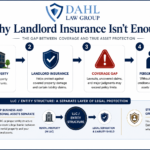
"My Insurance Will Cover It" - Why That Can Be a Risky Assumption for Landlords Quick Answer: Landlord insurance does not automatically make an LLC unnecessary. Insurance can pay certain covered claims, while a properly structured and maintained LLC can help separate rental-property liabilities from an owner's other assets. The two address different risks and often work best together as part of a broader Read More
Can Personal Expenses Qualify as Business Tax Write-Offs?
Executive Summary You generally cannot turn a wedding, birthday, anniversary, or other personal celebration into a business deduction simply by inviting clients or having your company pay the bill. IRC §162 allows ordinary and necessary business expenses, while IRC §262 generally disallows personal, living, and family expenses. Current rules under IRC §274 can impose additional restrictions on entertainment Read More
5 Ways California Business Owners Can Take Advantage of the Higher SALT Deduction
Executive Summary For 2026, the federal SALT deduction limit increases to $40,400 for most filers, subject to an income-based reduction when modified adjusted gross income exceeds $505,000. If you are a California business owner, the higher limit may make itemizing more valuable, but the result depends on your income, property taxes, state income taxes, and other deductions. California’s Pass-Through Entity Read More
Can Creditors Reach Your LLC Assets Through Reverse Veil Piercing in California?
Executive Summary California LLC assets are generally separate from an owner’s personal liabilities. That protection can weaken when the LLC is treated as the owner’s alter ego. Reverse veil piercing may allow personal creditors to pursue an LLC's assets in certain cases. Separate finances, keep accurate records, and document transactions to preserve entity separation. Following the Operating Agreement and Read More
Delaware Statutory Trusts & Asset Protection Questions Every Investor Should Consider
Executive Summary If you own appreciated investment real estate, a Delaware Statutory Trust (DST) could give you another option when completing a Section 1031 exchange. Revenue Ruling 2004-86 explains how an interest in a qualifying DST structure could be treated as an interest in real property for federal tax purposes. That treatment could support tax deferral when the other Section 1031 requirements are Read More